Overview

We Believe Investing Should Be Easy

The E-Valuator Risk Managed Strategy (RMS) Funds make investing easy for Investors by providing 6 distinctly different investment options spanning the efficient frontier spectrum of risk management from Very Conservative to Enhanced Growth.  Investors simply need to identify their personal level of acceptable volatility (risk) exposure, then invest accordingly in the RMS Fund(s) matching their tolerance level.

We Believe In a Systematic Approach to Intelligent Investing

We manage The E-Valuator Risk Managed Strategy (RMS) Funds with a disciplined, pragmatic approach seeking to maximize performance within a stated range of volatility, as measured by standard deviation. Our Meticulous Asset Allocation Process (MAAP) provides the guidance in the form of a “road map” through the asset allocation and diversification process.

We Strive To Simplify the Process

The E-Valuator Risk Managed Strategy (RMS) Funds were created to simplify a comprehensive asset management process, without sacrificing performance. Accordingly, each of The E-Valuator RMS Funds contains a complete asset management program packaged into an open-end mutual fund.

Downloads
 
Performance Report
 
Quarterly Commentary

As Seen In

The E-Valuator RMS Funds Are Not Typical Mutual Funds

The E-Valuator Software

The E-Valuator software systematically selects, monitors, and replaces (as needed) the underlying investments, i.e. ETF’s and open-end mutual funds.

M.A.A.P.

Meticulous Asset Allocation Process.  Establishes the “road map” for diversifying and allocating assets in a pragmatic, methodical manner.

Optimized for Return

Seeking to maximize performance at varying levels of risk along the efficient frontier while utilizing both Passive Management and Active Management.

Rebalancing

Underlying investments are rebalanced when their pro-rata balance of the Fund differs by +/-10% from their original allocation percentage.

Replacement

These fund-of-funds investments continually monitor, identify, and replace underlying investments whenever performance lags below the criteria set by the E-Valuator software.

Tax Harvesting

Proactively replace a lagging investment to potentially help reduce your taxable income.

NEWS & INSIGHTS
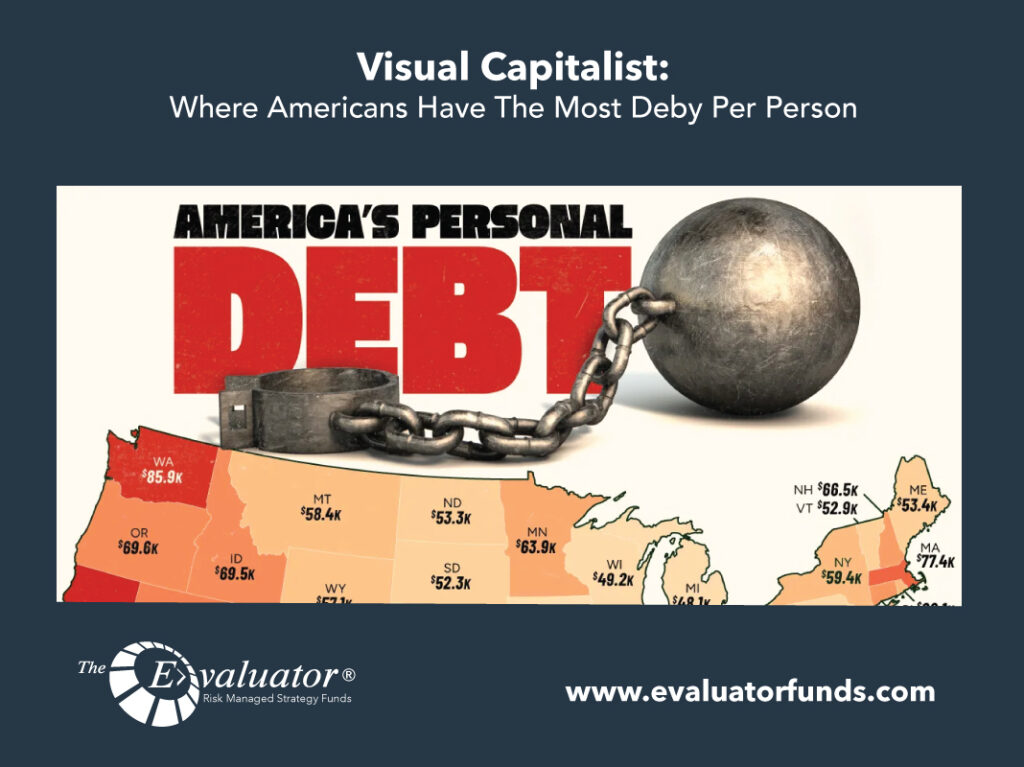
November 11, 2026Visual Capitalist: Which U.S. States Carry the Most Personal Debt? Personal Debt Across America: How States Compare Americans carry significant amounts of debt, but the average balance varies considerably depending on where they live. From mortgages and auto loans to credit cards and student loans, borrowing levels reflect differences in housing costs, economic conditions, and household financial needs. According to a recent Visual Capitalist analysis using fourth-quarter 2025 data from the Federal Reserve Bank of New York, Americans with a credit report carry an average of $63,200 in personal debt. Where Debt Levels Are Highest Washington, D.C., leads the nation with an average outstanding balance of $102,400 per person. Colorado follows at $92,690, while California ranks third at $87,850. Other areas reporting relatively high debt balances include Washington state, Hawaii, Utah, and Maryland. At the opposite end of the rankings, West Virginia has the lowest average personal debt at $37,850. Mississippi and Arkansas also report comparatively low borrowing levels. Housing Costs Play a Major Role Mortgages account for a substantial portion of household borrowing, making housing prices an important factor in explaining differences between states. In Colorado, mortgage debt represents approximately 78% of average personal debt, compared with 55% in West Virginia. Nationally, mortgages accounted for roughly 70% of the $18.8 trillion in outstanding household debt at the end of 2025. States with more expensive housing markets often have larger mortgage balances, which can push average debt totals higher. Does More Debt Mean Greater Financial Stress? Not necessarily. Although outstanding balances provide insight into borrowing patterns, they don’t tell the entire story about household financial health. Income, monthly payment obligations, interest rates, and repayment terms all influence whether debt is manageable. For example, a homeowner with a larger mortgage secured at a relatively low interest rate may face less monthly financial pressure than a borrower with a smaller balance carrying substantially higher interest costs. The Bigger Picture Differences in personal debt across the country highlight the relationship between housing affordability, borrowing costs, and household finances. While some states carry significantly larger balances than others, understanding the financial impact of debt requires looking beyond the total amount owed. Source: Visual Capitalist, Mapped: Where Americans Have the Most Debt Per Person, November 6, 2026. Data from the Federal Reserve Bank of New York, Q4 2025. [...] Read more...
November 10, 2026Jobs comeback The U.S. labor market rebounded in October, blowing past economists’ consensus forecast with a gain of 165,000 jobs, far above the 12-month average of 48,000 added per month. In addition, initial figures for August and September were revised upward by a total of 84,000 jobs, and unemployment slipped to 4.1% from 4.2% the previous month.   Still magnificent? For the first time since late 2022, quarterly earnings expectations for the Magnificent Seven group of mega-cap stocks are lower than forecasts for the rest of the 493 stocks in the S&P 500, according to FactSet. In the wake of mixed third-quarter reports from selected Mag Seven stocks, the group as a whole was expected to report a 22.6% growth rate overall for the quarter versus 32.6% for the other 493 companies.   Yield retreat The yield of the 10-year U.S. Treasury fell for the fifth week in a row, extending a decline that left it at 4.86% at Friday’s close, below an early October peak above 5.30%. Yields of 2-year and 30-year Treasuries also declined, finishing at 4.52% and 5.26%, respectively.   CPI & PPI ahead A Consumer Price Index report scheduled for release on Tuesday will show whether a recent trend of persistently elevated inflation extended into October. The most recent CPI report showed an annual rate of 3.7% in September—up from 3.4% the previous month. On Friday, a separate wholesale inflation report on the Producer Price Index is scheduled for release.   Read Full Article: https://www.jhinvestments.com/weekly-market-recap#market-moving-news [...] Read more...
November 6, 2026Why Treasury Yields May Matter More Than the Fed’s Next Decision While investors closely follow every Federal Reserve announcement, movements in the U.S. Treasury market may offer a better picture of what lies ahead for long-term investments. Recent fluctuations in the 10-year Treasury yield have attracted attention as markets respond to inflation, employment data, and expectations for future interest rate changes. Although the Federal Reserve influences short-term borrowing costs, longer-term Treasury yields are shaped by broader economic conditions and investor demand. Putting Higher Interest Rates Into Perspective Today’s Treasury yields may seem unusually high compared with the low-rate environment investors experienced over the past decade. However, historical trends tell a different story. During the 1990s, 10-year Treasury yields frequently ranged between 4% and 6%, yet the economy and stock market experienced periods of strong growth. This serves as a reminder that higher interest rates do not automatically prevent positive investment returns. New Opportunities for Bond Investors Higher Treasury yields may also create opportunities, particularly for investors seeking income. With yields reaching levels not seen in many years, fixed-income investments may offer more attractive income potential. Bonds could also regain some of their traditional role in helping balance portfolios during periods of stock market volatility. Looking Beyond the Fed Inflation, economic growth, and corporate earnings remain important factors in determining market direction. While upcoming Federal Reserve decisions may influence short-term market movements, maintaining a broader investment perspective can help investors evaluate opportunities and risks. For long-term investors, understanding Treasury yields and overall economic conditions may prove more valuable than trying to anticipate every interest rate announcement. Source: LPL Research, October 28, 2026. Based on commentary by Chris Fasciano, Chief Market Strategist at Commonwealth. [...] Read more...
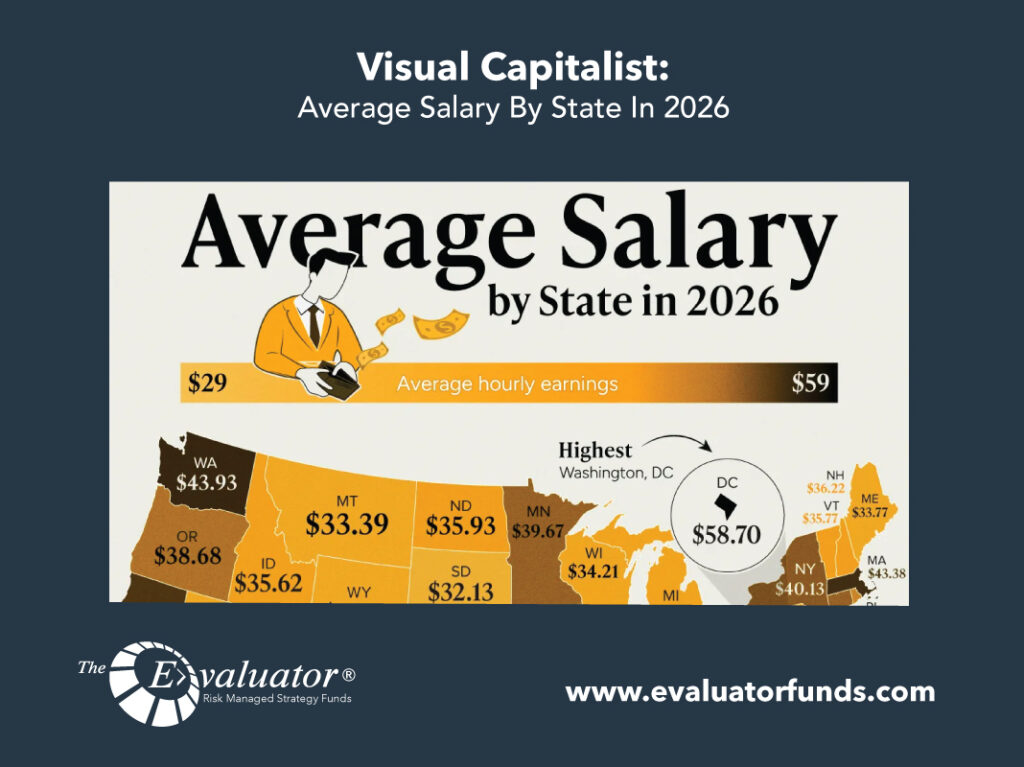
November 5, 2026Where Are Americans Earning the Most? Average hourly earnings continue to rise across the United States, but where you work can make a significant difference in how much you earn. According to data from the U.S. Bureau of Labor Statistics, average hourly earnings for private-sector workers reached $37.79 in August 2026, an increase of nearly 8% compared to 2024. Washington, D.C., led the nation with average hourly earnings of $58.70. Among the 50 states, Washington ranked highest at $43.93, followed by Massachusetts ($43.38) and California ($42.54). These areas benefit from a strong presence of higher-paying industries, including technology, finance, and professional services. At the other end of the spectrum, Mississippi reported the lowest average hourly earnings at $29.52, followed by Arkansas ($30.05) and West Virginia ($30.33). Higher Earnings Don’t Always Mean More Purchasing Power Although wages tend to be higher in the Northeast and West, living expenses and taxes can significantly affect how far those earnings go. For example, Minnesota averaged $39.67 per hour, above the national average, while Florida and Texas each averaged $36.37. While earnings have increased nationwide, inflation has reduced some of the benefit of those gains. Housing costs, state taxes, and everyday expenses all play a role in determining workers’ actual purchasing power. The takeaway: Where Americans earn the most isn’t necessarily where their money goes the furthest. Looking beyond wages to consider the cost of living, taxes, and inflation provides a more complete picture of financial well-being. Source: Visual Capitalist, “Mapped: Average Salary by State in 2026,” November 2, 2026. Data: U.S. Bureau of Labor Statistics, August 2026. [...] Read more...